Updated: Sep 9, 2026
Key Takeaways
- A $0 plan premium does not mean healthcare is free.
- The medical out-of-pocket limit excludes premiums and Part D spending.
- Returning to Original Medicare does not automatically guarantee Medigap access.
Understand the coverage arrangement
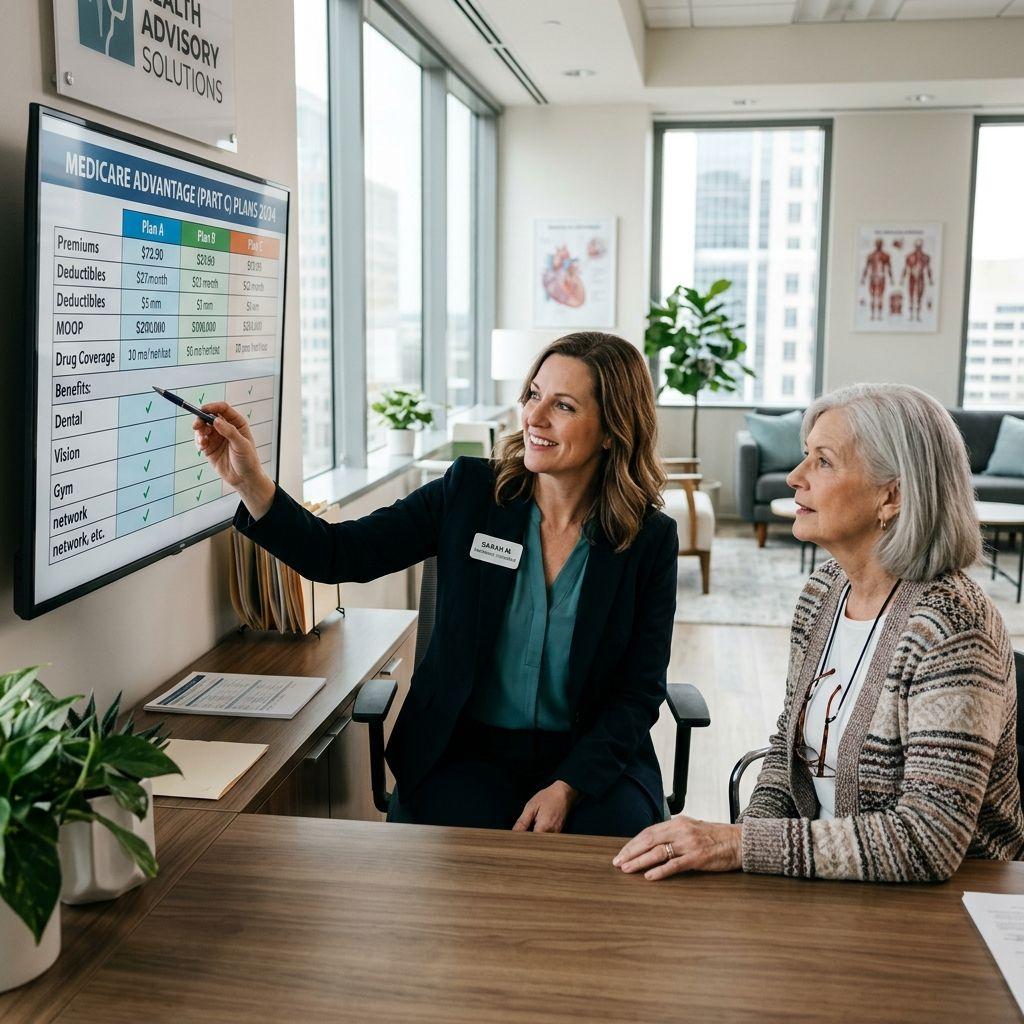
Medicare Advantage plans provide Medicare-covered Part A and Part B benefits through private insurers, with program exceptions such as how hospice is paid. Most include Part D drug coverage, but check the plan. HMO and PPO plans are common; other plan types also exist.
You generally continue paying the Part B premium even with a $0 additional plan premium. Copays, coinsurance, authorization requirements, and supplemental benefits vary by plan and year.
Get the Weekly Updates newsletter
Sign up for the latest financial advice, health news, and lifestyle updates.
Compare annual costs, not just premiums
For 2026, the federal maximum medical out-of-pocket limit for Medicare Advantage is $9,250 for in-network services; plans may set lower limits. Plans with a combined in- and out-of-network limit can have a maximum of $13,900. Use the actual plan's 2026 Evidence of Coverage to identify which limit applies.
These limits concern covered Part A/B medical cost sharing. Premiums, Part D drug spending, and noncovered services are separate. Do not interpret the medical limit as a cap on every healthcare expense.
Original Medicare has no general annual medical out-of-pocket maximum without other coverage. Its charges depend on the service: a hospital bill cannot simply be multiplied by 20%. For an outpatient illustration only, a $1,000 approved Part B amount with a met deductible and standard 20% coinsurance produces $200 before supplemental insurance. Inpatient rules differ.
Check access and treatment rules
| Question | What to verify |
|---|---|
| Providers | Exact doctors, hospitals, specialists, and facilities participating in this plan |
| Care rules | Referrals, prior authorization, and appeal procedures |
| Drugs | Formulary, pharmacy network, restrictions, and annual costs |
| Travel | Routine care outside the area and emergency or urgent coverage |
| Extra benefits | Eligibility, annual allowances, exclusions, and participating vendors |
HMO network rules include exceptions such as emergency care, urgently needed care, and out-of-area dialysis. PPO rules differ and out-of-network care may cost more. Original Medicare generally lets you use providers who accept Medicare, rather than literally any hospital or clinician.
Check Medigap rights before switching
You may be able to leave Advantage during an applicable enrollment period, but buying Medigap afterward is a separate question. Outside open enrollment or applicable guaranteed-issue or trial rights, medical underwriting can apply under state rules. Confirm access to the desired Medigap policy before cancelling the existing plan.
Use the enrollment-period guide. A person's current health alone does not determine the best plan; provider access, expected treatment, financial exposure, and future switching rights also matter.
Frequently Asked Questions
Can I freely switch to Original Medicare plus Medigap later?
Does the medical spending limit include all costs?
ARTICLE SOURCES
Retire Companion requires writers to use primary sources to support their work. These include white papers, government data, original reporting, and interviews with industry experts. We also reference original research from other reputable publishers where appropriate. You can learn more about the standards we follow in producing accurate, unbiased content in our editorial policy.
- Medicare. How Medicare works: Original Medicare and Medicare Advantage
- Centers for Medicare & Medicaid Services. CY 2026 MOOP and cost sharing limit calculations
- Medicare. Health Maintenance Organizations
- Medicare. Buying a Medigap policy
- Medicare. Medicare costs
Was this article helpful?
Your feedback helps us improve our resources.